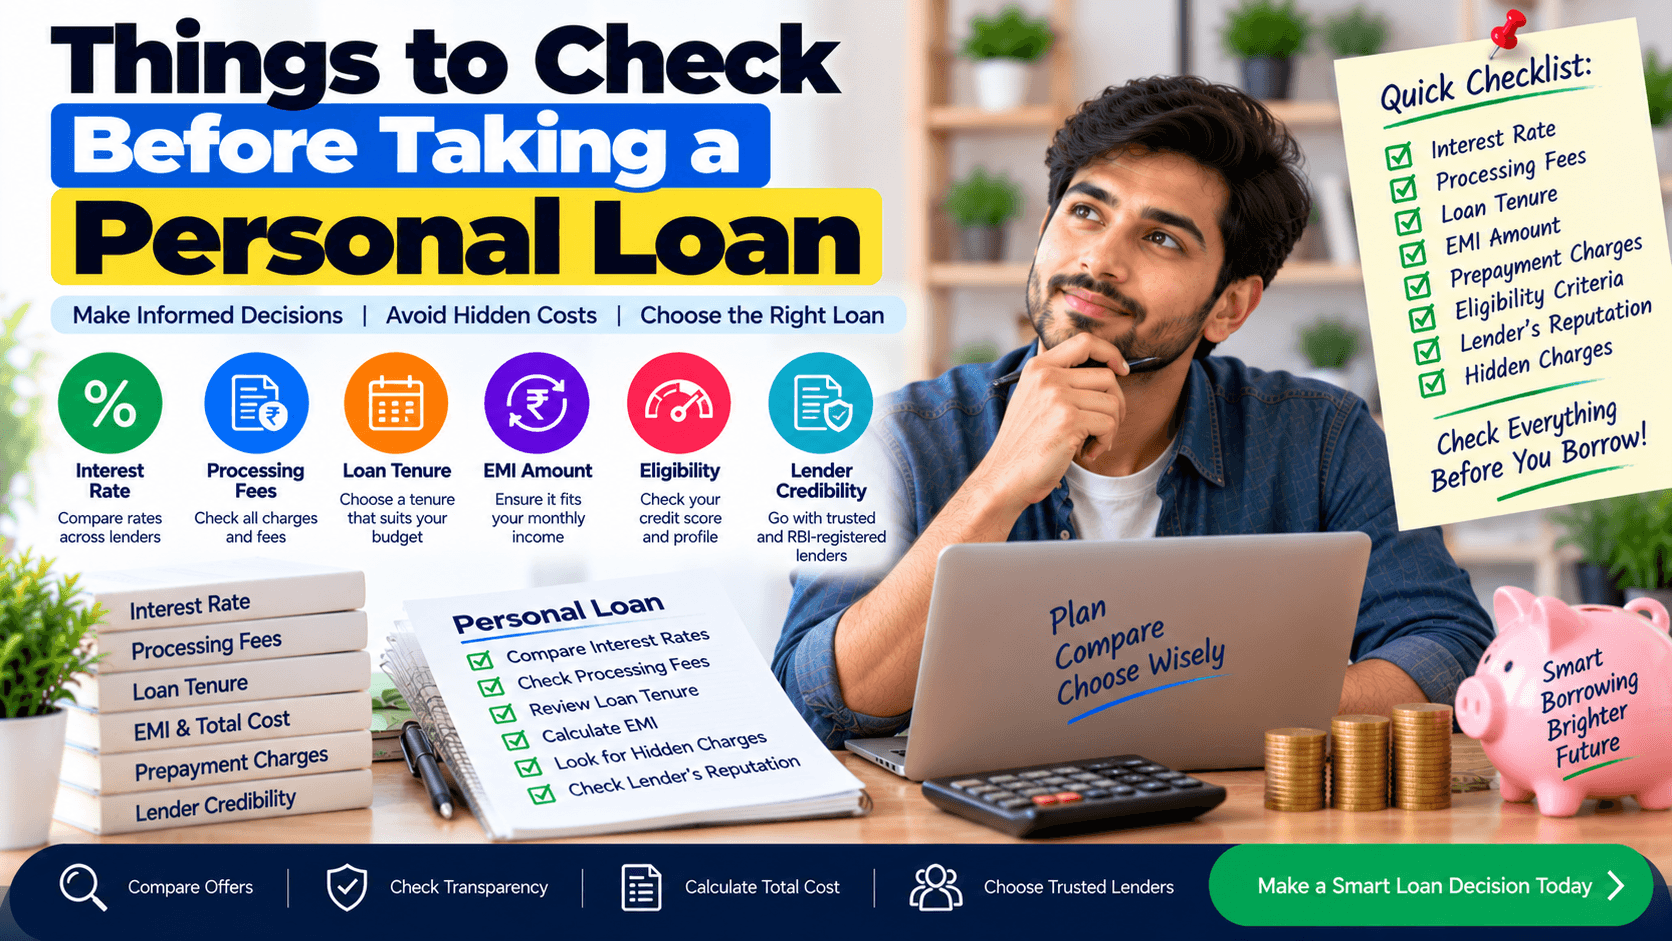
Personal loans can be a quick solution for emergencies, wedding expenses, home renovation, or debt consolidation. However, unlike a credit card, the interest rate is fixed and the repayment schedule is rigid. In the Indian banking landscape, where interest rates vary widely and processing fees can add up, taking a loan without proper due diligence can strain your finances for years.
Check your CIBIL/Equifax/Experian score – a score above 750 usually fetches the best rates.
Look for any discrepancies in your report (missed payments, duplicate entries) and get them corrected before applying.
Higher scores not only lower the interest rate but also increase the loan amount you may qualify for.
Fixed rate: The EMI stays the same throughout the tenure, making budgeting easier.
Floating rate: Usually linked to the RBI’s repo rate or MCLR. It can drop, but it can also rise, affecting your monthly outflow.
Compare the APR (annual percentage rate) rather than just the nominal rate to see the true cost.
Calculate the effective interest rate by adding processing fees, pre‑payment charges, and any insurance premiums.
Use online EMI calculators to see the impact of a longer tenure – lower EMI but higher overall interest.
Ask the lender for a breakdown of all charges in writing.
Shorter tenures (12‑24 months) reduce total interest but increase monthly EMI.
Longer tenures (48‑60 months) lower EMIs but increase the amount you pay overall.
Check if the bank allows partial pre‑payment or full foreclosure without penalties.
Most Indian banks require a stable income source (salary slip, ITR for self‑employed) and a minimum salary threshold (usually ₹25,000 – ₹30,000 per month).
Gather documents like PAN, Aadhaar, address proof, salary certificate, and bank statements ahead of time.
Some lenders also ask for a guarantor – understand the implications before agreeing.
Processing fees typically range from 0.5% to 2% of the loan amount, capped by RBI at a certain limit.
Some banks bundle a loan protection insurance; assess whether it adds real value or just inflates cost.
Read the fine print for any hidden charges like late payment fees or statement fees.
Opt for banks or NBFCs with transparent policies and good customer service ratings.
Check online reviews and forums (e.g., MyBankingExperts, BankBazaar) for real‑world borrower experiences.
Consider the turnaround time for disbursement – a quick release may be crucial in emergencies.
Unlike home loans, personal loans do not offer tax deductions on interest paid under Section 80C or 24.
However, if the loan is used for education, you might claim a deduction under Section 80E. Verify with a tax advisor.
Obtain your latest credit report and ensure the score is at least 750 for optimal rates.
Use an EMI calculator to decide the tenure that balances affordable EMIs with total interest.
Shortlist 3‑4 lenders (including both banks and reputable NBFCs) and compare APR, processing fees, and pre‑payment penalties.
Prepare all mandatory documents (PAN, Aadhaar, salary slips/ITR, bank statements) to avoid delays.
Read the loan agreement carefully; ask the loan officer to explain any clause you don’t understand.
If possible, negotiate a waiver of processing fees or a lower rate based on your credit profile.
Set up an automatic debit (ECS/NACH) to avoid late‑payment charges and improve your credit score.
Taking a personal loan in India can be a smart financial move when you need funds quickly and have a clear repayment plan. By scrutinising your credit score, total cost of borrowing, tenure, and lender terms, you protect yourself from hidden costs and future cash‑flow stress. Follow the checklist, stay informed, and choose a loan that aligns with your financial goals.